• ENQUIRE ONLINE OR CALL US
  • 08 8451 1500
    utf-logo1utf-iconutf-logo1utf-logo1
    • Home
    • Why Us
    • How it Works
    • Rates
    • News
    • Contact
    • Resources
      • Free Finance Review
      • Free Rate Check
      • Free Loan Calculators
      • Free Property Report
      • Latest News
      • Service Guarantee
      • Sponsorship Program
      • Submit a Referral
      • Key Personnel
      • Xpress Brands
        • Xpress Loans [AI]
        • Xpress Business Loans
        • Xpress Personal Loans
        • Xpress Car Loans
        • Xpress Home Loans
        • Xpress Senior Loans
      • Real Investar
        • FREE Property eBook
        • Dual Income Property
        • Real Investar Program
      • Other
        • Sitemap
        • IDR Policy
        • Privacy Policy
        • Terms of Service
        • Urbantech Group
    • Free Review
    ✕
    The RBA’s interest rate statement for November 2015
    Smart financing tips for property investors
    Show all

    Interest only vs principal & interest loans – which is better?

    November 10, 2015

    Should you convert interest only loans to principal & interest?

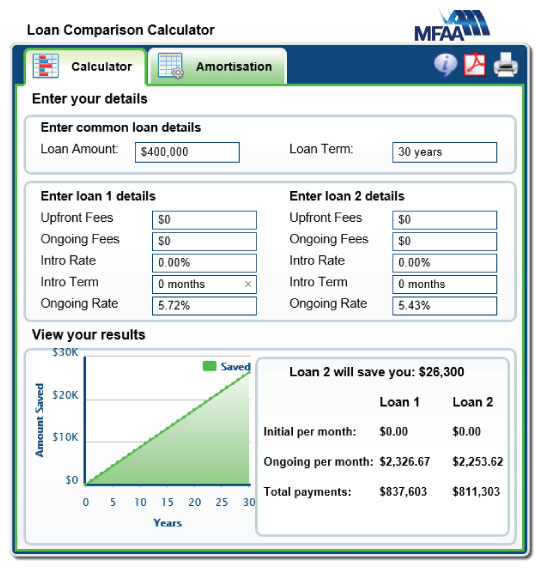
    For as long as I can remember ‘interest only’ loans have been priced the same as ‘principal & interest’ [P&I] loans, however that all changed not too long ago, when lenders began putting up interest only loan rates.

    As an example, if the standard variable interest rate on a NAB interest only loan is 5.72% the equivalent principal & interest home loan rate will be 5.43%.

    That’s a difference of 0.29%!

    Which begs the question – is it worth paying a premium to have an interest only loan?

    If you have an interest only home loan and you’re already making extra payments each month [either directly into your loan, line of credit or offset account] then you are in fact already paying principal and interest – so in this case you could be better off switching to a less expensive P&I home loan.

    Using the NAB example above you could expect to save $26,300 over the life of your loan by switching to the P&I rate.
    loan-comparison-p&i

    But there’s more…

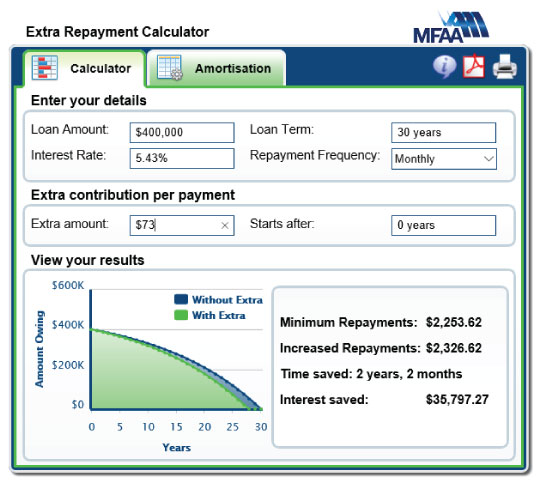
    The difference between monthly repayments on the 5.72% loan [$2,326.67] and 5.43% loan [$2,253.62] is $73.05 per month.

    While it doesn’t sound like much here’s what it looks like if you took the $73.05 saving and paid it into your loan each month in addition to your usual minimum repayment.
    extra-repayments-savings

    The result: an additional saving of $35,797 in interest and a reduction in your loan term of 2 years and 2 months.


    Why are interest only loans so popular?

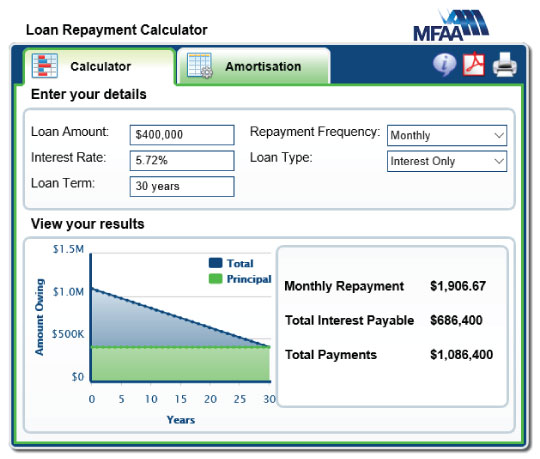
    The main reason is they’re cheaper… that is compared to an equivalent principal & interest loan the repayments are cheaper each month, as you are only paying off interest.

    Using the same example, even at the slightly higher rate of 5.72% the monthly repayments on an interest only loan are only $1,906.67 compared with $2,253.62 for the cheaper 5.43% P&I loan – that’s a difference of $346.95 per month.
    interest-only-loan-repayments

    From a lending perspective lower repayments improve your serviceability, allowing you to borrow more from lenders. So if you’re borrowing capacity is limited an interest only loan might help you borrow that extra bit of money you might need to buy the property of your dreams.

    Another reason interest only loans are popular with home owners is they allow you to lock in the lower monthly repayment while still giving you the ability to pay off as much loan principal as you like, whenever you like.

    This provides a level of flexibility for the person with variable income and/or expenses. For example, if cash flow is reduced for a few months you can just pay the minimum interest payment on your loan and when things pick up you can start making larger repayments again.

    Interest only loans are also ideal for property investors who want to use their residual savings and income to pay down their non-deductible home loan debt. Because from a tax perspective it doesn’t make sense to pay off deductible investment loan debt when you still have non-deductible debt, such as your home loan.

    In this case it makes sense for your investment loans to be interest only so that any remaining income can be used to pay down your cheaper and non-deductible principal & interest home loan.


    >> For expert guidance on whether you should consider converting your interest only loans to P&I call 8451 1500 or email us.


    PS. Free Loan Calculators – if you want to have a play around with the numbers yourself, we’ve recently uploaded a whole suite of loan calculators to our website.

    Sam & Matt
    Urbantech Group
    Adelaide Mortgage Broker +plus more…
    Share

    Related posts

    September 3, 2026

    Why most investors stop at one property!


    Read more
    August 25, 2026

    Making your home work in retirement!


    Read more
    August 13, 2026

    A retirement option many Australians overlook!


    Read more
    • Facebook
    • Twitter
    • LinkedIn
    • Instagram
    • YouTube
    • Google

      Newsletter Signup

      Name:

      Email:

      Free Finance Review

      Whether you're buying or refinancing, we'll make sure you get the best loan going!

      LEARN MORE

      Free Property EBook

      Learn how to get out of bad debt and build a passive retirement income.

      LEARN MORE

      Recent News

      • Why most investors stop at one property!
        September 3, 2026
      • Making your home work in retirement!
        August 25, 2026
      • A retirement option many Australians overlook!
        August 13, 2026
      • The RBA’s interest rate statement for August 2026
        August 11, 2026
      • No two borrowers are the same!
        July 27, 2026
      • Archive 2007-2011
      • Business Loans
      • Car Loans
      • Education Services
      • Events
      • Finance
      • Financial Planning
      • Home Loans
      • Insurance
      • Loan Hub
      • Market Updates
      • News Alerts
      • Newsletter
      • Personal Loans
      • Property Investment
      • Property Sales
      • RBA Rate Decisions
      • Resources
      • Senior Loans
      • Urbantech Updates

      Quick Links

      • Free Finance Review
      • Free Rate Check
      • Free Loan Calculators
      • Free Property Report
      • Free Property eBook
      • Real Investar Program
      • Service Guarantee
      • Sponsorship Program
      • Submit a Referral
      • Key Personnel
      • Sitemap

      FREE FINANCE REVIEW   Click Here   |   CALL 08 8451 1500   |   EMAIL info@urbantechfinance.com.au

      231 South Rd, Mile End SA

      08 8451 1500

      info@urbantechfinance.com.au

      • Facebook
      • Twitter
      • LinkedIn
      • Instagram
      • YouTube
      • Google

      Quick Links

      • Free Finance Review
      • Free Rate Check
      • Free Loan Calculators
      • Free Property Report
      • Free Property eBook
      • Real Investar Program
      • Service Guarantee
      • Sponsorship Program
      • Submit a Referral
      • Key Personnel
      • Sitemap

      Latest News

      • Why most investors stop at one property!
        September 3, 2026
      • Making your home work in retirement!
        August 25, 2026
      • A retirement option many Australians overlook!
        August 13, 2026
      • The RBA’s interest rate statement for August 2026
        August 11, 2026
      • No two borrowers are the same!
        July 27, 2026

      © Urbantech Finance (Est. 2004) All Rights Reserved.   |   Website Design & SEO by Internet Marketer Inc.   Terms   |   Privacy Policy

      Urbantech Group Pty Ltd trading as Urbantech Finance is a credit representative (Credit Representative No. 397554)
      of BLSSA Pty Ltd (Australian Credit Licence No. 391237)

      Personal Loans   |   Car & Equipment Loans   |   Business Loans   |   Senior Loans

            Newsletter Signup

            Name:

            Email: