• ENQUIRE ONLINE OR CALL US
  • 08 8451 1500
    utf-logo1utf-iconutf-logo1utf-logo1
    • Home
    • Why Us
    • How it Works
    • Rates
    • News
    • Contact
    • Resources
      • Free Finance Review
      • Free Rate Check
      • Free Loan Calculators
      • Free Property Report
      • Latest News
      • Service Guarantee
      • Sponsorship Program
      • Submit a Referral
      • Key Personnel
      • Xpress Brands
        • Xpress Loans [AI]
        • Xpress Business Loans
        • Xpress Personal Loans
        • Xpress Car Loans
        • Xpress Home Loans
        • Xpress Senior Loans
      • Real Investar
        • FREE Property eBook
        • Dual Income Property
        • Real Investar Program
      • Other
        • Sitemap
        • IDR Policy
        • Privacy Policy
        • Terms of Service
        • Urbantech Group
    • Free Review
    ✕
    Footy Tips 2012 – starts soon!
    Wishing you a safe and happy Easter break!
    Show all

    The RBA’s interest statement for April…

    April 3, 2012

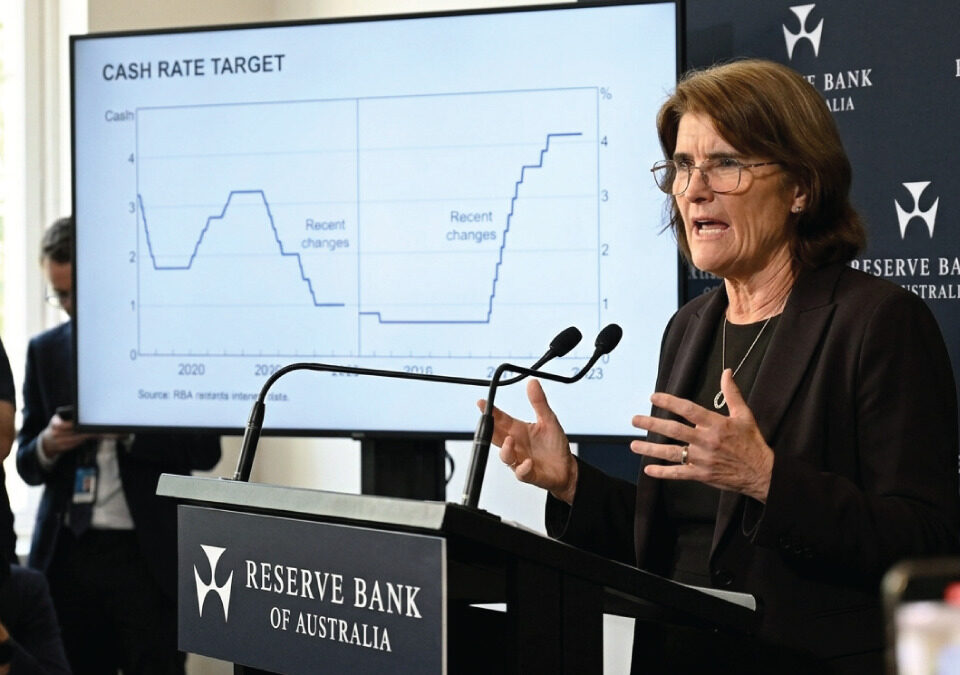
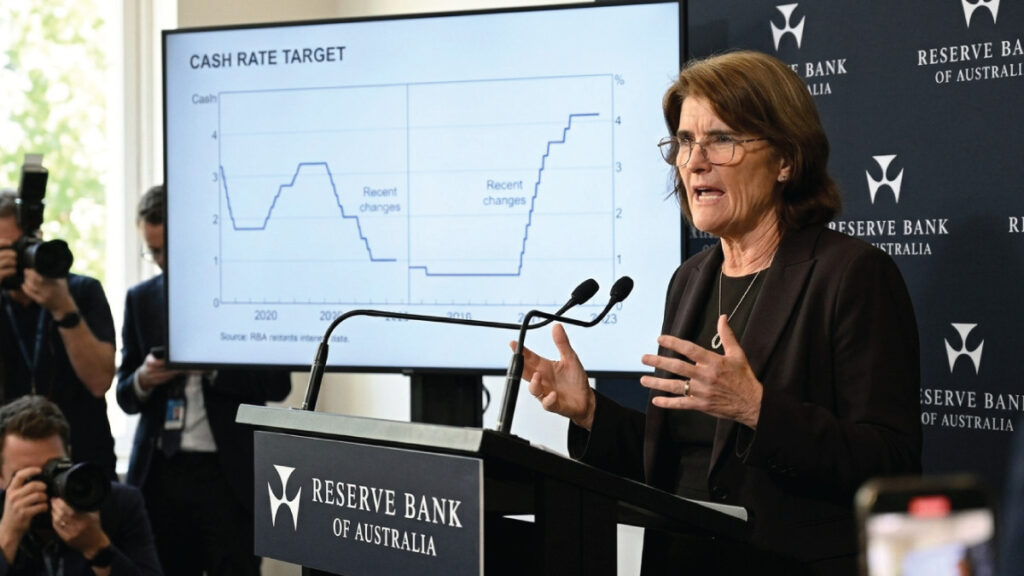
    At its meeting today, the Board decided to leave the cash rate unchanged at 4.25 per cent.  

    Statement by Glenn Stevens: Recent information is consistent with the expectation that the world economy will grow at a below-trend pace this year, but does not suggest that a deep downturn is occurring. Several countries in Europe will record very weak outcomes, but the US economy is continuing a moderate expansion. Growth in China has moderated, as was intended, and is likely to remain at a more measured and sustainable pace in the future. Conditions around other parts of Asia softened in 2011, partly due to natural disasters, but are not showing signs of further deterioration. Some moderation in inflation has allowed policymakers in the region to ease monetary policies somewhat. Commodity prices declined for a few months last year and are noticeably off their peaks, but have been relatively stable for a while now, at quite high levels. Australia’s terms of trade have peaked, though they remain high. 

    Financial market sentiment has generally continued to improve in recent weeks and capital markets are supplying funding to corporations and well-rated banks. At the margin, wholesale funding costs are tending to decline, though they remain higher, relative to benchmark rates, than in mid 2011. But the task of putting European banks and sovereigns onto a sound footing for the longer term remains large and Europe will remain a potential source of adverse shocks for some time yet.

    In Australia, growth in domestic demand ran at its fastest for four years in 2011, driven by private spending. Nonetheless the balance of recent information suggests that output growth was somewhat below trend over the year. There are differences in performance between sectors, and considerable structural change is occurring. Labour market conditions softened during 2011, though the rate of unemployment has been little changed for some time.

    Interest rates for borrowers remain close to their medium-term average. Credit growth remains modest. Housing prices have shown some signs of stabilising recently, after having declined for most of 2011, but generally the housing market remains soft. The exchange rate has remained high over recent months, even though the terms of trade have declined somewhat.

    In underlying terms, inflation was around 2½ per cent in 2011. CPI inflation was higher than that but will fall over the next quarter or two. It is currently expected that inflation will be in the 2–3 per cent range over the coming one to two years. This forecast abstracts from the effects of the carbon price and also embodies an assumption that productivity growth in the economy increases somewhat as a result of the structural change now occurring. At its next meeting, the Board will have the opportunity to reassess the outlook for inflation, taking into account not only data on demand and output but also forthcoming information on prices.

    The Board eased monetary policy late in 2011. Since then, its judgement has been that, with growth expected to be close to trend, inflation close to target and lending rates close to average, the setting of monetary policy was appropriate. The Board’s view was also that, were demand conditions to weaken materially, the inflation outlook would provide scope for easier monetary policy. At today’s meeting, the Board judged the pace of output growth to be somewhat lower than earlier estimated, but also thought it prudent to see forthcoming key data on prices to reassess its outlook for inflation, before considering a further step to ease monetary policy.

    Need help with your finances or want to discuss your how interest rate changes could affect your situation? We’re as close as your phone – just call us on 8451 1500

    Cheers,

    Sam
    Share

    Related posts

    August 11, 2026

    The RBA’s interest rate statement for August 2026


    Read more
    June 16, 2026

    The RBA’s interest rate statement for June 2026


    Read more
    May 5, 2026

    The RBA’s interest rate statement for May 2026


    Read more
    • Facebook
    • Twitter
    • LinkedIn
    • Instagram
    • YouTube
    • Google

      Newsletter Signup

      Name:

      Email:

      Free Finance Review

      Whether you're buying or refinancing, we'll make sure you get the best loan going!

      LEARN MORE

      Free Property EBook

      Learn how to get out of bad debt and build a passive retirement income.

      LEARN MORE

      Recent News

      • Why most investors stop at one property!
        September 3, 2026
      • Making your home work in retirement!
        August 25, 2026
      • A retirement option many Australians overlook!
        August 13, 2026
      • The RBA’s interest rate statement for August 2026
        August 11, 2026
      • No two borrowers are the same!
        July 27, 2026
      • Archive 2007-2011
      • Business Loans
      • Car Loans
      • Education Services
      • Events
      • Finance
      • Financial Planning
      • Home Loans
      • Insurance
      • Loan Hub
      • Market Updates
      • News Alerts
      • Newsletter
      • Personal Loans
      • Property Investment
      • Property Sales
      • RBA Rate Decisions
      • Resources
      • Senior Loans
      • Urbantech Updates

      Quick Links

      • Free Finance Review
      • Free Rate Check
      • Free Loan Calculators
      • Free Property Report
      • Free Property eBook
      • Real Investar Program
      • Service Guarantee
      • Sponsorship Program
      • Submit a Referral
      • Key Personnel
      • Sitemap

      FREE FINANCE REVIEW   Click Here   |   CALL 08 8451 1500   |   EMAIL info@urbantechfinance.com.au

      231 South Rd, Mile End SA

      08 8451 1500

      info@urbantechfinance.com.au

      • Facebook
      • Twitter
      • LinkedIn
      • Instagram
      • YouTube
      • Google

      Quick Links

      • Free Finance Review
      • Free Rate Check
      • Free Loan Calculators
      • Free Property Report
      • Free Property eBook
      • Real Investar Program
      • Service Guarantee
      • Sponsorship Program
      • Submit a Referral
      • Key Personnel
      • Sitemap

      Latest News

      • Why most investors stop at one property!
        September 3, 2026
      • Making your home work in retirement!
        August 25, 2026
      • A retirement option many Australians overlook!
        August 13, 2026
      • The RBA’s interest rate statement for August 2026
        August 11, 2026
      • No two borrowers are the same!
        July 27, 2026

      © Urbantech Finance (Est. 2004) All Rights Reserved.   |   Website Design & SEO by Internet Marketer Inc.   Terms   |   Privacy Policy

      Urbantech Group Pty Ltd trading as Urbantech Finance is a credit representative (Credit Representative No. 397554)
      of BLSSA Pty Ltd (Australian Credit Licence No. 391237)

      Personal Loans   |   Car & Equipment Loans   |   Business Loans   |   Senior Loans

            Newsletter Signup

            Name:

            Email: